Mobile Game Monetization Models and Strategies That Actually Work in 2026
Making money moves, minus the guesswork: how to pick a monetization mix that fits your genre, your economy, and your team.
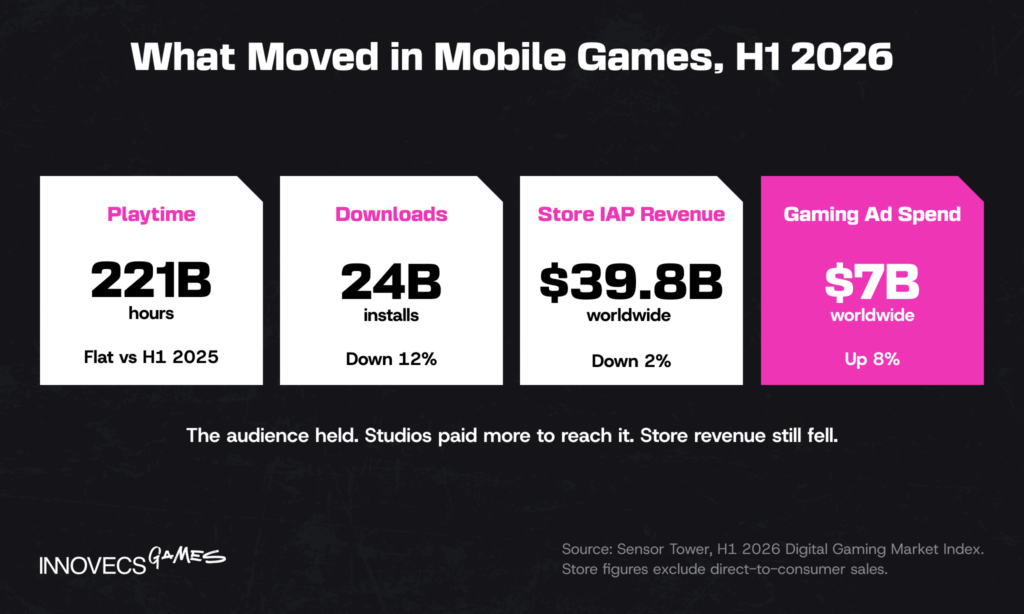
Players didn’t stop playing. They put 221 billion hours into mobile games across the first half of 2026, level with the same six months a year earlier, and the stores still took 2 percent less from them: $39.8 billion in IAP against $40.6 billion, on 12 percent fewer downloads, according to Sensor Tower. Studios meanwhile spent 8 percent more on advertising, $7 billion of it. So the audience held, studios paid more to reach it, and the revenue still landed somewhere the store charts don’t show.
That gap is the whole story of mobile game monetization right now. Growth used to come from buying more installs. It now comes from what happens to a player in the ninety days after install, and from where the transaction is processed. Get either one wrong and a game with healthy retention still posts a flat P&L, which is a uniquely demoralizing way to have a good year.
How Do Mobile Games Actually Make Money in 2026?
Strip it back and mobile game monetization answers one question: how does time spent become money received. Five channels answer it today, and most studios run at least two of them, whether that’s purchases inside the app, advertising, a subscription, a paid download, or direct sales through a web shop the studio owns outright. On most projects it shows up as a line in the GDD that somebody will fill in later. It behaves more like a subsystem: it has telemetry, a release cadence, and failure modes of its own, and none of that gets designed by being written down late.
The scale is worth stating plainly. Newzoo forecast a resilient market back in 2022 and was broadly right about direction: the global games market reached $188.8 billion in 2025, with mobile at roughly $103 billion, about 55 percent of the total. What has changed is the shape underneath. Sensor Tower’s State of Mobile 2026 put store-level game IAP at just under $82 billion for 2025, up 1.3 percent, while non-gaming apps overtook games in store spending for the first time. The App Store booked $52.5 billion in gaming revenue, growth of 0.6 percent.
Adjust argued years ago that multiple revenue sources were becoming a requirement rather than an optimization. That call aged well, but the reason has shifted. Diversification used to be insurance against a bad quarter for one channel. Now it’s a structural response to three things happening at once: install costs that no longer fall, store commissions that studios can legally route around, and an ad stack that lost most of its user-level signal and rebuilt itself on modeling. Choosing among mobile game monetization models is no longer a launch decision you make once and revisit at your leisure.
Which Monetization Models Should Your Mobile Game Use?
Five mobile game monetization models cover almost everything shipping today, and the honest answer to “which one” is usually “two of them, weighted.” What follows is one section per model, with the trade-off stated rather than buried, because that’s the part that decides whether a model survives contact with your genre.
| Model | Where revenue comes from | Best fit | The trade-off you inherit |
|---|---|---|---|
| In-app purchase (IAP) | A small share of players buying currency, progression, or cosmetics | Strategy, RPG, puzzle, social casino | Revenue concentrates in a few percent of users, so one balance patch can move the quarter |
| Rewarded and interstitial ads | Impressions served to non-payers and light payers | Casual, hypercasual, hybrid casual | Ad load competes with session quality and can suppress IAP conversion |
| Subscription | Recurring fee for content, removal of ads, or a pass | Live games with a steady content pipeline | You now owe the player something new every month, forever |
| Premium (one-time purchase) | Paid download | Narrative, puzzle, ports of proven PC or console titles | No second revenue event, and mobile discovery punishes a price tag |
| Hybrid | Two or more of the above, segmented by player | Most free-to-play games above casual | Complexity: you’re running two economies that interfere with each other |
Read the right-hand column first. It’s the one people skim past on the way to picking a model, then rediscover in month four when the numbers stop making sense.
Subscription Monetization Model
A subscription model on mobile means the game is free to download while a recurring fee unlocks content, removes ads, or bundles access to a catalog. Udonis breaks the format into subscription-only plans, auto-renewable plans the player has to cancel manually, non-renewing plans, and umbrella services such as Apple Arcade and Google Play Pass that cover many titles at once.
Here’s the uncomfortable 2026 update. Subscriptions won mobile, and games mostly didn’t get the win. Sensor Tower recorded $167 billion in total store spending for 2025, up 10.6 percent, with non-gaming apps at $85.6 billion against $81.8 billion for games. That crossover was driven by subscription-first categories: AI assistants, short-form drama, streaming. Game subscription services grew, but they grew as a distribution deal, not as a business model most studios can run themselves. Our read, and we’d be glad to be argued out of it: for anyone under publisher scale, a platform subscription is funding with an audience attached, not a monetization model. Treat it as the former and it’s a good deal.
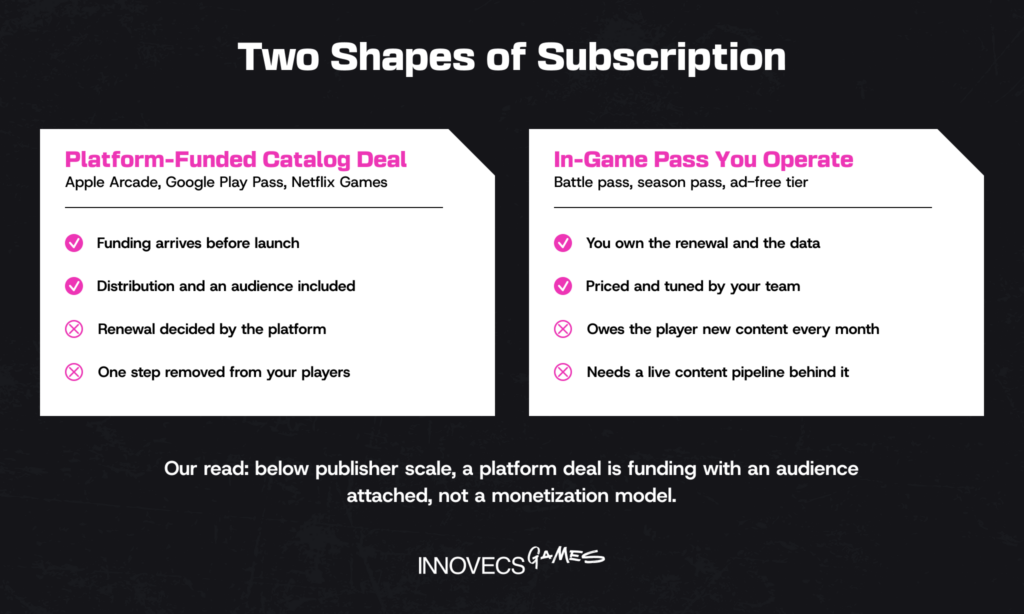
The dependency risk is real and it has a name attached. Ustwo Games told mobilegamer.biz in January 2026 that it is deliberately weaning itself off Apple Arcade and Netflix funding after Netflix pulled Monument Valley 3 six months into its run. CEO Maria Sayans put it as being “one step removed from your audience, and you are dependent on their content strategy.” The game left Netflix in July 2025 and returned that December as a premium release on iOS and Android with an expansion attached, which worked out, but on a timetable the studio never chose. A platform-funded subscription deal is revenue you don’t control the renewal of. In-game passes, the battle-pass style subscription you operate yourself, are a different and generally safer animal.
“Pay to Play”: One-Time Purchase Games
Paid mobile games charge once, ship without ads, and live or die on the store page. Stardew Valley has held that line on mobile for years, and the logic behind it hasn’t changed: a known quantity, a fair price, no interruptions, and no drip of offers. Players who pay upfront skip the buyer’s remorse that a badly tuned free-to-play economy manufactures.
The format had a better 2025 than most people noticed. AppMagic counted roughly 750 premium releases on mobile, up 77 percent year over year, with Balatro taking $21.3 million from 3.1 million mobile downloads, Slay the Spire $13.7 million, and Human Fall Flat $7.8 million. Premium still accounts for about 4 percent of mobile downloads against 96 percent free-to-play, so read that as a healthy niche rather than a comeback.
Where the volume goes hasn’t changed. Valve took 13 percent more through Steam in 2025 than the year before, per Sensor Tower’s State of Gaming 2026, while the App Store managed 0.6 percent. The premium buyer still exists in large numbers. He’s on PC, and increasingly he expects mobile to be the cheap or free version of something he already owns.
Premium pricing works on mobile in two situations that are worth naming precisely. First, a port of a title with an existing audience, where the store page does no persuasion because the reputation already did it. Second, a short, complete, design-forward game where the absence of monetization pressure is the product. Outside those, a paid download on mobile is a decision to trade almost all of your reach for a clean conscience. Sometimes that’s the right trade. It’s rarely the profitable one.
Rewarded Video Ads and Player Engagement
Everything from here assumes the opposite bet: give the game away, and earn from players who may never open their wallet.
Rewarded video ads let a player choose to watch in exchange for something: a continue, currency, a doubled reward, a temporary boost. The consent is the whole mechanism. Udonis has tracked strong player preference for the format for years, and Unity’s analysis across eight high-DAU titles found viewers 4.5 times more likely to make a purchase than non-viewers, with thirty-day retention landing between 53 and 68 percent against a 13 percent benchmark. Retention gaps that wide usually say more about who opts in than about what the ad does, so read them as a signal of engagement rather than a recipe for it. The format still earns its slot. It just doesn’t manufacture players who weren’t going to stay.
Advertisers have shifted their creative mix to match. Video now accounts for 53.7 percent of creatives by Sensor Tower’s 2026 count. Rewarded ads sit at 17.7 percent, having grown nearly 54 percent in a year, and playable ads at 13.3 percent, close to double where they were. Interstitial ads and banner ads still carry real volume. What they don’t carry is the growth, which has gone entirely to formats a player either opts into or can put his hands on.
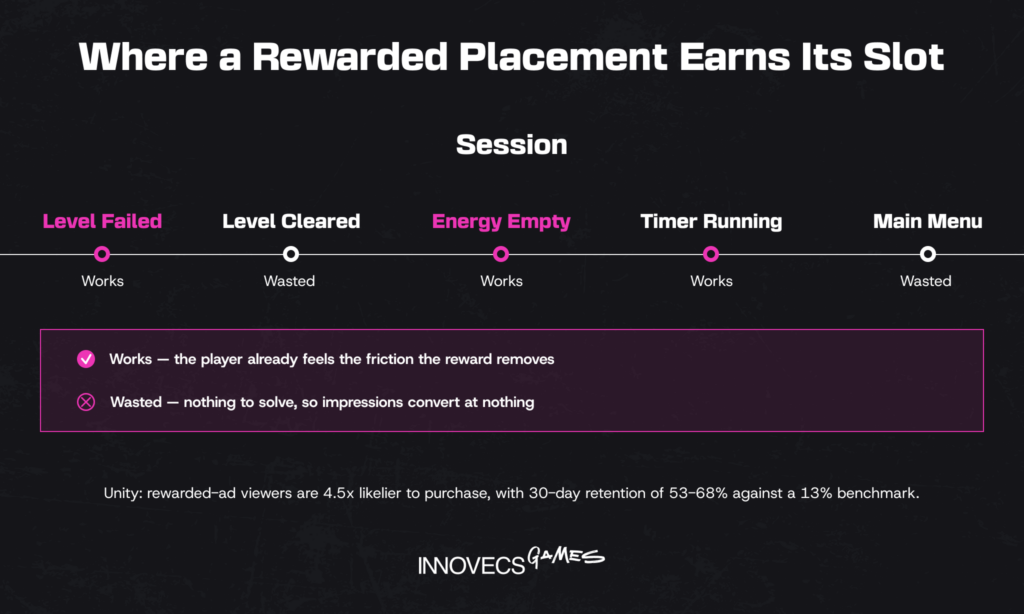
Two design constraints decide whether rewarded ads help or quietly hurt. The reward has to matter enough to be worth thirty seconds and not so much that it undercuts the equivalent in-app purchase, which is a balance problem, not an ad-ops problem. And placement has to sit at a moment of friction the player already feels: a failed level, an empty energy bar, a timer he doesn’t want to wait out. Offerwalls follow the same rule at a longer time horizon. Drop a rewarded placement into a moment where nobody is stuck and you’ll get impressions that don’t convert and a retention curve that looks slightly worse for no revenue. Nobody has ever been talked into wanting a reward they had no use for.
In-App Purchases and Revenue Metrics
Udonis, a mobile games marketing service, makes a point that survives every platform change: in-app purchases perform when they’re offered at the moment the player needs help. Stuck on the same level for the tenth time is a sales conversation. The main menu isn’t.
Measuring whether it works comes down to a small set of numbers your team should be able to recite from memory, and in our experience roughly half of them can:
- DAU (daily active users)
- ARPPU (average revenue per paying user)
- Conversion rate, the share of players who ever pay
- LTV (lifetime value), and the predicted version of it you use to bid on installs
- Retention rate and churn, which set the ceiling on everything above
Genre decides how far those metrics can go, and the spread is wider than most roadmaps assume. Sensor Tower’s H1 2026 store data:
| Genre | Store IAP revenue, H1 2026 | Notes |
|---|---|---|
| Strategy | $9.27 billion | Largest genre by IAP, driven by 4X and mid-core economies |
| Puzzle | $8.07 billion | Produced almost the entire absolute market gain, around $1.3 billion |
| RPG | $6.12 billion | Strong ARPPU, heavily exposed to the shift toward direct sales |
Puzzle producing nearly all of the market’s absolute growth is the figure worth sitting with for a minute. A genre with modest ARPPU and enormous reach outgrew genres earning ten times as much per payer, because it kept converting new players while everyone else got better and better at monetizing the ones they already had. There is a limit to how much more you can extract from a person who has already given you their credit card, and 2025 was the year a lot of teams found it.
Hybrid Monetization: Combining Multiple Models
It means running ads and IAP in the same title, segmented so they don’t collide. It stopped being a casual-games tactic somewhere around 2024, and the 2025 numbers make the case better than any argument. Hybrid-casual was the only segment to grow IAP revenue, and hypercasual was the only segment whose downloads didn’t decline. Everything in between shrank.
Ad revenue concentrates almost entirely at the casual end:
| Segment | Ad revenue, Feb to Apr 2026 |
|---|---|
| Hypercasual | $2.02 billion |
| Casual | $2.01 billion |
| Hybrid casual | $827 million |
| Mid-core | $190 million |
Source: Sensor Tower. Mid-core earning less than a tenth of hypercasual from ads is not a failure of mid-core ad ops. It’s a rational choice: those players are worth more as payers than as impressions.
Which is exactly where hybrid models get hard. The player who would have spent $40 this month should not be shown an ad that hands him the same resource for free. The player who will never spend a cent should be shown as many as he’ll tolerate. That segmentation runs on predicted LTV, applied within the first few sessions, and it’s the single most common place a hybrid setup goes wrong. Teams ship the ad units, skip the segmentation, watch total revenue rise for six weeks as ad revenue arrives, then find IAP has quietly dropped by more than the ads brought in. There’s no elegant way around this one: you need the model, and you need it early. If you’re choosing between a hybrid setup without segmentation and a single clean model, take the single model. Half a hybrid is not half the revenue, it’s a slow leak with a dashboard on top.
Matching a Model to Your Genre
Genre decides more of this than craft does. A puzzle team and a 4X team can run identical live ops discipline and still land an order of magnitude apart on revenue per payer, because their players show up for different lengths of time with different reasons to spend. The table below is where most games start, not where they finish.
| Genre | Session shape | Primary model | Secondary | The number that tells you it works |
|---|---|---|---|---|
| Puzzle | Short, frequent, very high volume | Ads | Lives, boosters, light IAP | Ad ARPDAU alongside D7 retention |
| Hypercasual and hybrid casual | Very short, enormous volume | Ads | A cheap pass, cosmetics | Ad ARPDAU against install cost |
| Strategy and 4X | Long, daily, deep economy | IAP | Battle pass, direct sales | ARPPU and payer retention |
| RPG and gacha | Long, event-driven spikes | IAP | Direct sales | Event revenue per active payer |
| Social casino | Medium, habitual | IAP | Direct sales | Payer concentration in the top cohort |
| Simulation | Medium, daily | Hybrid, segmented | Ads for non-payers | Conversion to first purchase |
| Narrative and premium | Finite, one pass through | Paid download | DLC or a sequel | Units sold and refund rate |
The table lies in exactly one place: it assumes your game is cleanly one genre. Plenty aren’t, and the games that sit between two rows are the ones where the monetization decision is worth real argument rather than a default.
Not Sure Which Monetization Model Fits Your Game? Let’s Talk
Genre, retention curve, and content cadence usually narrow the choice to two viable options, and picking between them is a design decision before it’s a business one. Send us your build or your economy doc, and we’ll tell you which mobile game monetization setup fits and what it costs to run.
How Does Ad Tracking Power Mobile Game Ads?
You can’t optimize what you can’t attribute, and the identifiers that used to make attribution trivial have been reshaped twice in five years. The short version for 2026: Apple’s signal is fully modeled and moving to a new framework, and Google’s identifier survived a deprecation everyone had already planned around.
Personalized mobile game ads still depend on device identifiers, Apple’s IDFA and Google’s GAID, which let publishers connect an install to the campaign that produced it. App Tracking Transparency made IDFA opt-in in 2021 and the industry rebuilt around SKAdNetwork’s aggregated postbacks. Apple has since introduced AdAttributionKit, which extends the same privacy-preserving approach and adds re-engagement measurement, and it now runs alongside SKAdNetwork rather than replacing it overnight.
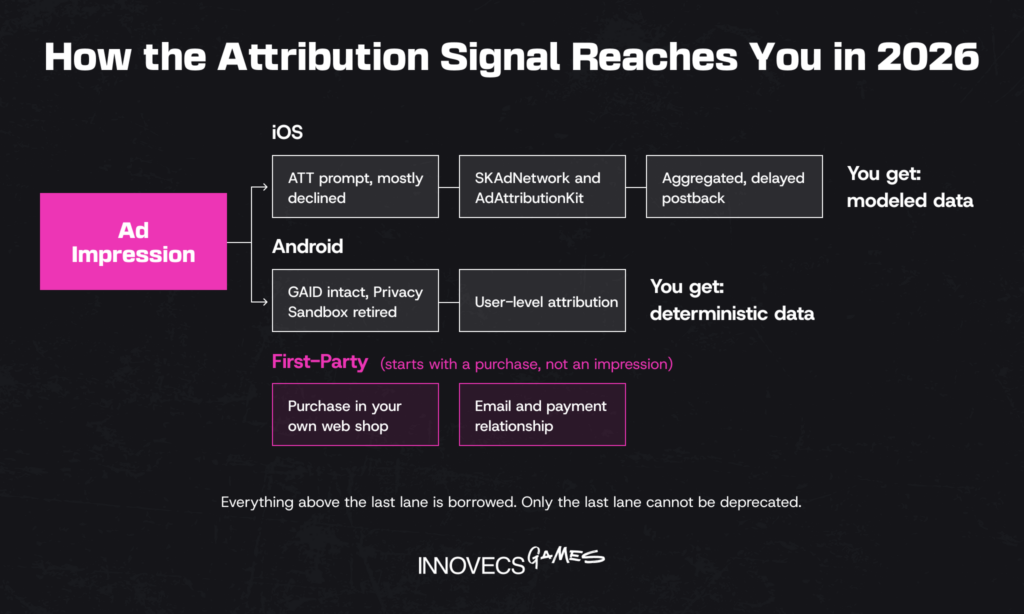
On Android, the plot twist. Google announced on 17 October 2025 that it is retiring most Privacy Sandbox technologies, including the Attribution Reporting API and Topics on both Chrome and Android, after adoption failed to materialize. Branch had documented what Play Store attribution looked like without GAIDs. That future receded. GAID is still there, still doing the work, and the deprecation timeline a lot of teams budgeted around has quietly evaporated. Somewhere there is a 2024 roadmap with a line item for this, and it can be deleted.
| Signal | Status in 2026 | What it means for your ad stack |
|---|---|---|
| IDFA | Opt-in under ATT, low consent rates | Treat user-level iOS data as a bonus, not a baseline |
| SKAdNetwork | Live, aggregated postbacks | Still the backbone of iOS campaign measurement |
| AdAttributionKit | Live, runs alongside SKAdNetwork | Adds re-engagement attribution; plan the migration, don’t rush it |
| GAID | Unchanged, Privacy Sandbox retired | Android keeps user-level attribution for the foreseeable future |
| First-party data | Growing fast, especially via web shops | The only identifier you own outright |
The last row is the one that changes strategy rather than tooling. A player who buys through your own store gives you an email address, a payment relationship, and an event stream nobody can deprecate. Everything else on that list is borrowed.
Practically, the stack most studios end up with is an attribution platform, a mobile analytics SDK, ad mediation across several ad networks, and a modeled LTV layer sitting on top. Wire that stack correctly and mobile game ads become a budget you can steer; wire it badly and it becomes a report you can only read after the fact. Getting it right before soft launch is unglamorous work, and it’s where most of the recoverable money hides. Our game development team handles that integration on live titles often enough to know where it usually breaks: mismatched event taxonomies between the analytics SDK and the mediation layer, always discovered about three weeks into a campaign, never before.
How Is AI Changing the Way Mobile Games Monetize?
That modeled layer is where AI actually entered monetization, as prediction rather than generation, and four applications of it are already running at scale.
Predictive LTV modeling. Models estimate a player’s eventual spend from the first few sessions, then feed that estimate into UA bidding and into what the player is shown in-game. Academic work has moved past single-game models to cross-game dynamic mixture approaches published at the ACM Web Conference 2026, which matters because most studios have more data across a portfolio than inside any one title.
Dynamic offers. The same prediction decides which bundle appears in the shop, at what size, and when. A player flagged as a likely payer sees a starter pack; one flagged as ad-supported sees a rewarded placement instead. This is the mechanism behind hybrid segmentation working at all.
AI-driven pricing. Price ladders adapt by region, cohort, and elasticity rather than sitting on a fixed tier list. The gains here are real but smaller than vendors claim, and they attract regulatory attention faster than any other application on this list.
Automated ad optimization. Creative selection, bidding, and network allocation are now largely machine-run, and AppMagic found 56 percent of the top 100 grossing games using AI in ad creation during 2025. The mediation decision that used to be a weekly ops meeting is a continuous auction.
Where it doesn’t help is worth saying with equal clarity. AI won’t design your economy, and a model trained on a broken sink-and-faucet balance will confidently optimize you deeper into it. It won’t tell you whether an offer is predatory, and the line between good segmentation and something a regulator will eventually name is a judgment call your team owns. The industry mood is instructive here: GDC’s 2026 State of the Game Industry surveyed more than 2,300 professionals and found 36 percent using generative AI tools while 52 percent believe it’s having a negative effect on the industry. Both numbers are true at once, and the split runs along a clean line: prediction and optimization get adopted quietly, generation gets fought over loudly. Our position, for whatever it’s worth from a team that ships this: the cost of producing a prediction has collapsed, and the cost of being right about what to do with one hasn’t moved a cent. The studios getting value here are the ones that already knew what question they were asking. If you want the broader picture, we covered it in our piece on AI in game development.
What Regulators Are Changing About In-Game Purchases
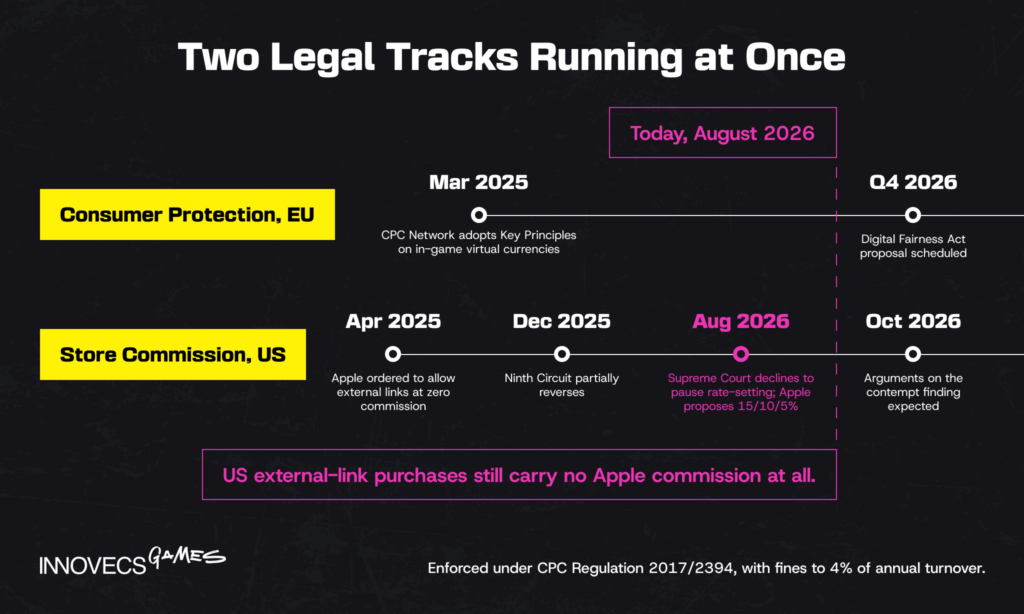
Personalization has a ceiling, and in Europe it is being written down. In March 2025 the EU’s Consumer Protection Cooperation Network, led by the Dutch ACM and the Norwegian Consumer Authority, adopted Key Principles on in-game virtual currencies. They are not legislation. They describe how national authorities intend to apply consumer law that already exists, under a regulation that carries fines of up to 4 percent of annual turnover.
Four of the seven principles land directly on shop design:
- Show the real-money price of an item alongside the soft-currency price.
- Don’t obscure cost through layered currencies or forced exchanges.
- Don’t oblige a player to buy a currency bundle larger than the item he wants.
- Honor the 14-day right of withdrawal, including on unused currency, and set defaults that protect minors.
Read those four together and you’ll recognize the patterns they describe. The currency ladder priced so no bundle ever matches an item exactly. The pack that leaves the player forty gems short of the thing he opened the shop to buy. Those are not edge cases in the guidance; they are the worked examples. Our view is that this was always coming, and that the industry spent a decade treating one particular design pattern as a law of nature. The teams that find the transition cheapest will be the ones whose economy still works when the price is legible.
The larger piece is still in front of us. The Digital Fairness Act sits in the Commission’s work programme for the fourth quarter of 2026. On current drafts it could ban paid loot boxes outright or require parental consent for minors, restrict how virtual currency and items are bundled, mandate a reminder before every automatic subscription renewal, and regulate autoplay and pay-to-win incentive design. Each of those is a storefront rebuild, an age-verification path, or both.
None of it is settled, and building today for the strictest version of a proposal that may soften is a real way to waste a quarter. The price-display requirement is the exception worth designing for now regardless of how the rest lands: it is cheap to implement, it applies under law that is already in force, and no plausible version of the final rules removes it.
What Can AAA Mobile Games Teach Us About Monetization?
Compliance changes what the shop looks like. It doesn’t change who collects the payment, and that’s the part the top of the charts has been quietly moving. Every blockbuster gets there through a combination of models, and the combination keeps changing. The ecosystem started without any in-app purchase option at all, as ironSource documented: Tap Tap Revenge won App Store Game of the Year in 2008 on a subscription, and Super Monkey Ball shipped at $9.99 and moved 300,000 copies in twenty days. Freemium replaced both within about four years.
The 2026 equivalent of that shift isn’t a new model. It’s a new venue. miHoYo’s store revenue fell 24 percent in H1 2026 and Roblox’s fell 29 percent, and in both cases the cause was success rather than decline: PocketGamer.biz reported that roughly 57 percent of miHoYo’s US revenue now flows through direct-to-consumer channels the store charts never see. Playtika books 39 percent of revenue through D2C. Stillfront reached 46 percent of bookings. DoubleDown went from 15 percent to 52 percent in a single year.
The legal ground moved underneath that and still hasn’t settled. Apple was ordered in April 2025 to permit external payment links at zero commission, won a partial reversal at the Ninth Circuit that December, then in August 2026 failed to get the Supreme Court to pause the rate-setting proceedings. Apple has proposed 15 percent for standard apps, 10 percent for subscription renewals and partner programs, and 5 percent for Small Business Program developers. Judge Yvonne Gonzalez Rogers has to approve a rate, Epic gets roughly sixty days to answer, and arguments on the underlying contempt finding are expected in October 2026. Until all that lands, US external-link purchases carry no Apple commission at all. Publishers moved during the gap rather than waiting, on the reasonable bet that whatever the court sets won’t exceed 30 percent.
What Selling Direct Actually Involves
The channel is no longer experimental. Appcharge’s 2026 research sized D2C at $17 billion, about 15 percent of a $113.3 billion mobile IAP market, with a median revenue uplift of 15 percent across adopters and 35 percent among the leaders. Unity counts web shops at 80 percent of top strategy titles and 75 percent of top action titles.
The take rate is the easy part to understand and the misleading part to plan around:
| Route | Platform commission | Note |
|---|---|---|
| Standard in-app purchase | 15 to 30 percent | The baseline everyone is trying to leave |
| Link out from inside the app, US | 0 percent right now | Only while the Epic rate-setting is unresolved |
| Link out from inside the app, EU | Roughly 10 to 20 percent | Under the DMA terms |
| Player arrives at the shop directly | 0 percent | And this is the hard one |
That last row is the whole business case, and it is also where most programs stall. Half of publishers in the Appcharge sample named player awareness as their biggest D2C obstacle and another 41 percent named acquisition. The shop is not the problem. Getting anyone to visit it without breaking a store rule is.
What you take on in exchange for the commission is a list that rarely makes the pitch deck: merchant-of-record fees or your own VAT registration and remittance across every market you sell in, chargebacks and payment fraud, a refund and support path that used to be Apple’s problem, and account linking solid enough that a purchase made on a laptop lands in the right save file on a phone. Net of all that, the 30 percent you stopped paying is not 30 percent you get to keep. It’s worth doing at scale, and it’s worth being honest that the players who migrate first are almost entirely players who were already paying you. Below a certain revenue line the whole thing is a tax registration project wearing a growth initiative’s clothes. Where that line sits is a real conversation, and it is further up than most vendor decks suggest.
The Ad Formats That Still Earn Their Placement
For everyone else, the lesson from the top of the charts is narrower than “build a web shop.” It’s that the ad formats which engage still outperform the ones that interrupt, and that hasn’t changed in a decade:
- Playable ads let the player try the mechanic before installing, which is why the format nearly doubled its share of creatives in a year. Our playable ads guide covers what goes into building one.
- Rewarded ads trade attention for value with the player’s consent, and correlate with higher purchase rates rather than lower.
- Interstitial ads still convert at scale when they sit at natural breaks, and tank retention when they don’t.
- Banner ads are the low-yield, low-friction option, and developers on Reddit have been arguing about whether they’re worth the screen space for the better part of a decade without reaching a verdict.
When Each Monetization Decision Has to Be Made
Most of what goes wrong with monetization was decided correctly, just too late. The cost of a monetization choice is not the work it takes; it’s the work it invalidates. Switching from an ads-led model to an IAP-led one after the vertical slice is not a shop feature, it’s a progression redesign, and progression is what the whole build sits on.
| Phase | What gets decided | What it blocks | Cost of deciding late |
|---|---|---|---|
| Concept and pre-production | Model family: ads-led, IAP-led, or premium | Economy design, session length targets, shop art budget | Highest. Changes the design of the game, not the storefront |
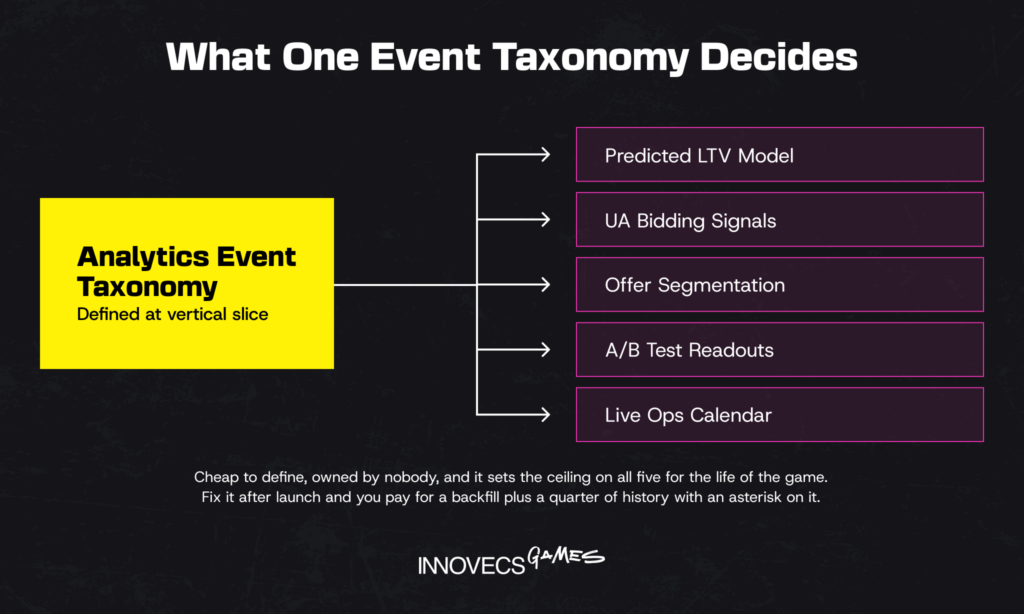
| Vertical slice | Currency structure, sink and faucet skeleton, analytics event taxonomy | Every measurement you will ever run | High and invisible. A wrong taxonomy is discovered during the first campaign |
| Pre-soft-launch | Analytics, mediation and attribution SDKs, first shop build, price ladder, age rating and store compliance | Soft-launch reads | Moderate. Mostly integration time, but it delays the only data that matters |
| Soft launch | Predicted-LTV model, ad placements, segmentation rules, A/B infrastructure | Global launch confidence | Moderate. Skipping segmentation here is the mistake that shows up as ads eating purchases |
| Global launch | Live ops calendar, event economy, D2C decision | Year-one revenue shape | Recoverable, but each month of live ops without a calendar is a month of flat revenue |
| Post-launch | Regional pricing, offer personalization, regulatory review | Margin | Ongoing. This one is supposed to keep moving |
Read the third column rather than the first. Teams generally know which phase they’re in; what they miss is which downstream decision they have already made by not making it.
The analytics event taxonomy in row two deserves singling out. It’s cheap, unglamorous, owned by nobody in particular, and it silently sets the ceiling on every optimization for the rest of the game’s life. It is the single most common thing we’re asked to fix on a title that’s already live, and by then fixing it means a backfill nobody budgeted for and a quarter of historical data with an asterisk next to it. If you take one operational thing from this article, take that one.
How Innovecs Games Helps You Build a Profitable Monetization Strategy
Mobile game monetization strategies fail in production, not in the deck, so we build and operate the systems behind them. That means economy design and balancing, shop and offer implementation, ad mediation and SDK integration, analytics event taxonomy, live ops tooling, and the A/B infrastructure to test a price ladder without shipping a client update and waiting a week for review. Teams plug into your existing pipeline and share responsibility for milestone delivery, which is a different arrangement from handing over a spec and waiting.
Where Mobile Game Monetization Strategies Usually Break
Three patterns account for most of the rescue work that reaches us. An economy tuned for a genre the game has since drifted away from. An ad integration shipped without player segmentation, so ads eat purchases. And an analytics setup where the events the ad network optimizes toward aren’t the events that predict revenue, which buys the wrong players very efficiently and reports it as a win.
If you’re building from scratch, our mobile game development services cover the full production path with monetization designed in rather than retrofitted. If you have a team and a gap, game development outsourcing fills the specific role, whether that’s a monetization designer, an ad ops engineer, or a data scientist to build the LTV model.
And if you sit somewhere between the two, or you just want a second read on numbers that aren’t behaving, write to us. We’ll tell you what we’d do with it, including the cases where the honest answer is that you don’t need an outside team for this one.
FAQ
What is mobile game monetization?
Every system that turns playtime into money, taken together. That means the shop, the ads, the subscription if you run one, the paid download if you charge for one, and now the web shop where you sell around the store entirely. Calling mobile game monetization a commercial function undersells it, because the economy, the difficulty curve and the offer schedule are one machine seen from three angles, and pulling on any of them moves the other two. What teams underestimate is how much of this has to live in the client. You can’t configure your way to a shop the game was never built to hold.
What monetization models work best for mobile games in 2026?
None of them, universally. Ads carry casual and hypercasual, purchases carry mid-core and strategy, and hybrid-casual, which runs both at once, grew faster in 2025 than either. Strategy titles booked $9.27 billion in store IAP across the first half of 2026 and puzzle titles $8.07 billion, per Sensor Tower, and yet puzzle produced nearly the entire market’s absolute gain. So the biggest genre and the fastest-growing one are not the same genre. Rank the candidates against your own retention curve and session length rather than against whatever the last GDC talk recommended.
How do in-app purchases work in mobile games?
Someone buys currency, or progression, or a hat, or the right to skip a timer. That transaction runs through the store’s payment system, or increasingly through the studio’s own web shop, and the store has historically kept 30 percent of it, which is the entire reason direct-to-consumer channels exist. Low conversion is the design rather than a fault in it: a few percent of players generate most in-app purchases revenue, so ARPPU and lifetime value tell you far more than headline revenue does. Timing beats size. A modest pack offered to a player who is stuck will outperform a generous one offered on the main menu, reliably enough that you can plan around it.
Why do players respond well to rewarded video ads?
Consent, mostly. He chooses to watch, he knows what he is getting, and he gets it the moment the video ends, which turns an interruption into a trade. Advertisers noticed before publishers did: Sensor Tower has the format up nearly 54 percent as a share of creatives in 2026. Unity took the other half of the question across eight high-DAU titles and found viewers 4.5 times likelier to buy than non-viewers, which makes the format a bridge into paying rather than a replacement for it.
Is hybrid monetization better than relying on one model?
Usually, and only with segmentation in place. Run ads and purchases side by side without deciding who sees which, and you hand free resources to precisely the players who would have paid for them. With segmentation working, a hybrid setup picks up money from the ninety-plus percent who never buy anything, and hybrid-casual was the only category to grow IAP revenue across 2025. Without it, month one looks excellent, everyone congratulates each other, and then purchases fall by more than the ads ever brought in. We have watched that sequence play out more than once.
How much can a mobile game earn from ads?
Genre decides this far more than execution does. Across February to April 2026, hypercasual publishers pulled $2.02 billion out of advertising while mid-core publishers managed $190 million, a gap of better than ten to one that says almost nothing about how well either group runs ad ops. Impressions drive the number, so short sessions, enormous volume and low purchase intent are what actually pay. Mid-core teams should treat ads as a supplement rather than a line they can build a plan on, and any projection saying otherwise is really a projection about some other game.
What’s the difference between IDFA and GAID for ad tracking?
One belongs to Apple, one to Google, and in 2026 they are not in comparable shape. Apple put IDFA behind an explicit opt-in in 2021 under App Tracking Transparency, so iOS measurement now arrives as aggregated, delayed postbacks through SKAdNetwork and AdAttributionKit. GAID kept working at the user level, and when Google retired most Privacy Sandbox technologies in October 2025 it took with them the deprecation timeline half the industry had already written into a roadmap. Practically: modeled data on iOS, deterministic data on Android, and two separate ways of being wrong.
How do I choose the right monetization model for my game’s genre?
Session length and retention first. The model second. Short sessions with shallow progression push you toward ads; a long session with an economy worth engaging with pushes you toward purchases; a live content pipeline makes a pass viable on top of either one. The genre table earlier on this page gives a starting point per genre and the metric that will tell you whether it took. A game sitting cleanly inside one genre can follow it, while one sitting between two, and plenty do, should plan a hybrid and budget the segmentation work now rather than meeting it in month four.
How is AI changing the way mobile games monetize?
Through prediction, not through content. A model reads a player’s first few sessions, guesses what he will be worth, and that guess then drives both the bid to acquire him and the offer he meets in the shop. Dynamic offers and automated ad optimization run continuously now, where a team used to gather and decide on Tuesdays. Adoption is real and contested at once: GDC’s 2026 survey put 36 percent of professionals on generative AI tools and 52 percent on the view that it is damaging the industry, and almost none of that argument is about the prediction half.
Can AI personalize in-game offers and pricing automatically?
Yes, and it is among the more mature things AI does here. A model sorts players by predicted spend, then serves each group its own bundle, price point and discount depth, adjusting as behavior moves. The engineering is the easy half. Somebody on your team still has to say where personalization stops and exploitation starts, and at what point regional pricing stops looking like fairness and starts looking like opacity. Don’t hand that one to a model.
Ready to Maximize Your Mobile Game Monetization? Let’s Talk
You know your retention curve and your content roadmap. We know which economy, ad, and offer systems hold up once a game is live and how long each takes to build. Tell us the game and the timeline, and we’ll scope the work.